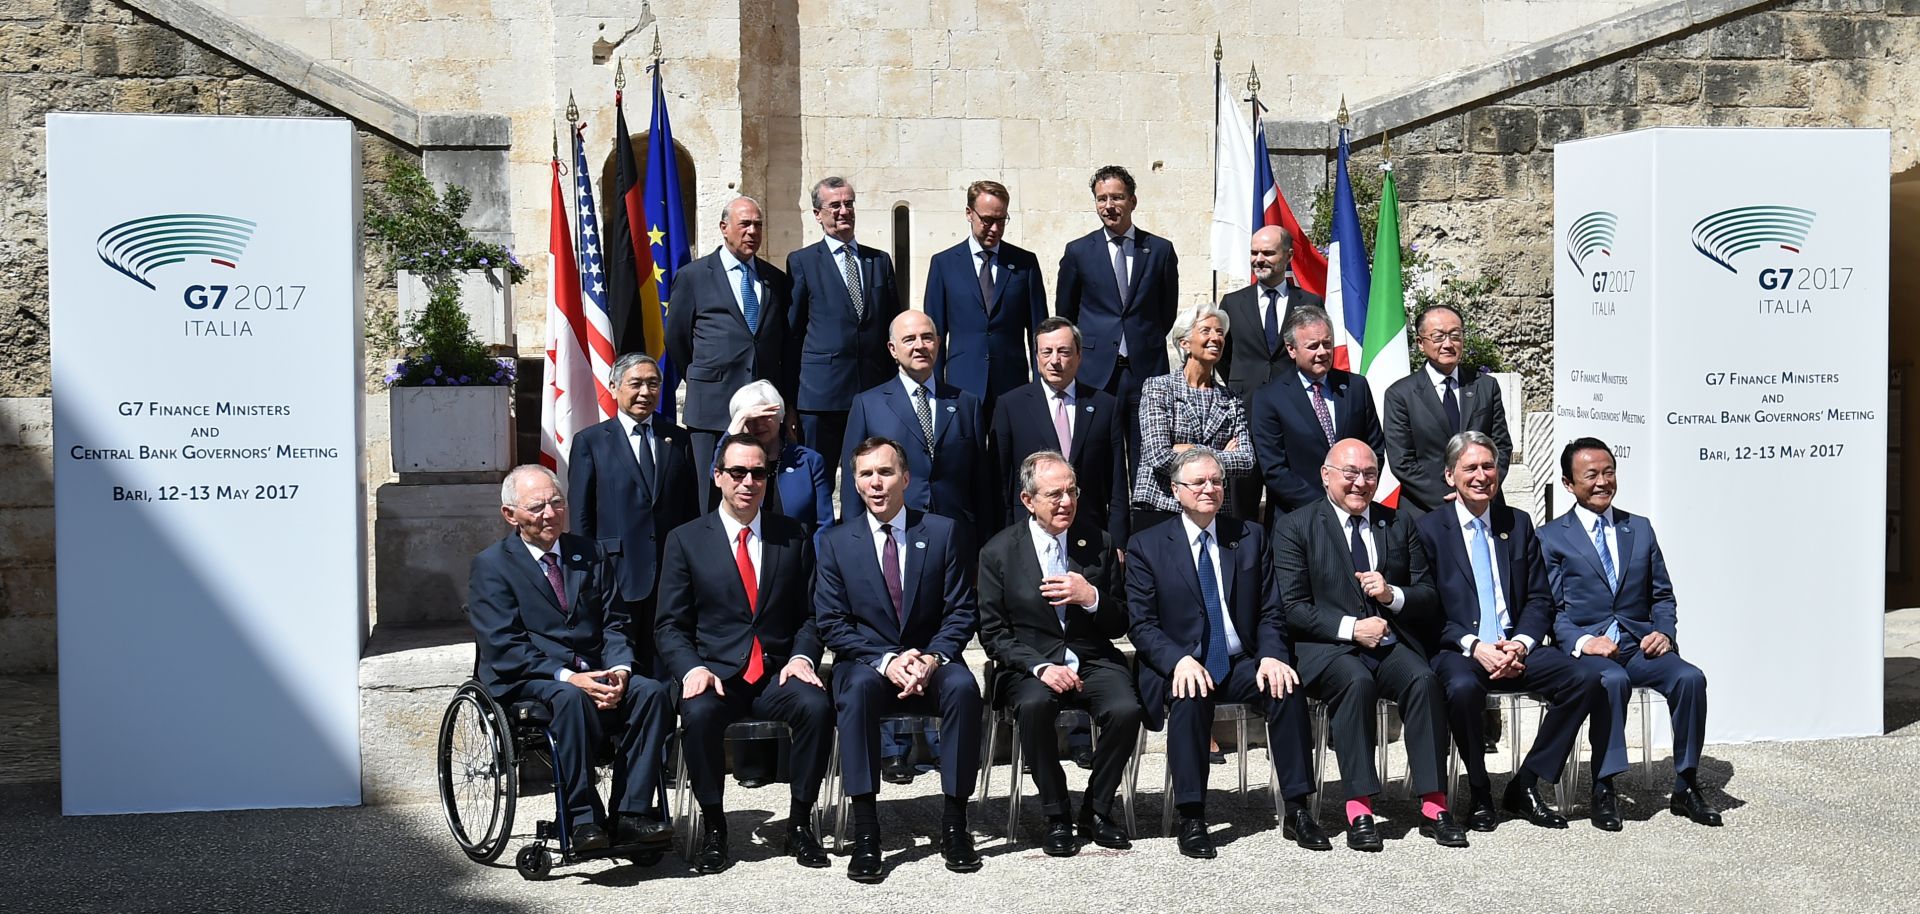
The Financial Action Task Force, banking and other financial leaders gather during a May 2017 meeting of G-7 finance ministers in Bari, Italy. The Paris-based Financial Action Task Force, established to fight money laundering and terrorism, recently declared Pakistan's reform efforts on the matter inadequate while it gave Iran more time to meet its guidelines.
The Financial Action Task Force (FATF) is a 37-member intergovernmental organization that focuses on setting global standards for combating money laundering and terrorist financing. Headquartered in Paris, it holds three plenary sessions a year – in February, June and October. During its latest meeting, which ran June 24-29, the FATF added Pakistan to its "gray list" while it continued to suspend countermeasures on Iran. What's at Stake for Pakistan? Economic Context. Pakistan unsuccessfully sought to avoid being placed on the FATF's watchlist of "jurisdictions of strategic deficiencies," the so-called gray list. The FATF encourages its members to apply countermeasures against gray-listed countries that can include heightened scrutiny for international banking transactions. For Pakistan, the new listing will increase its risk profile at a time when the country's macroeconomic woes necessitate external financing.