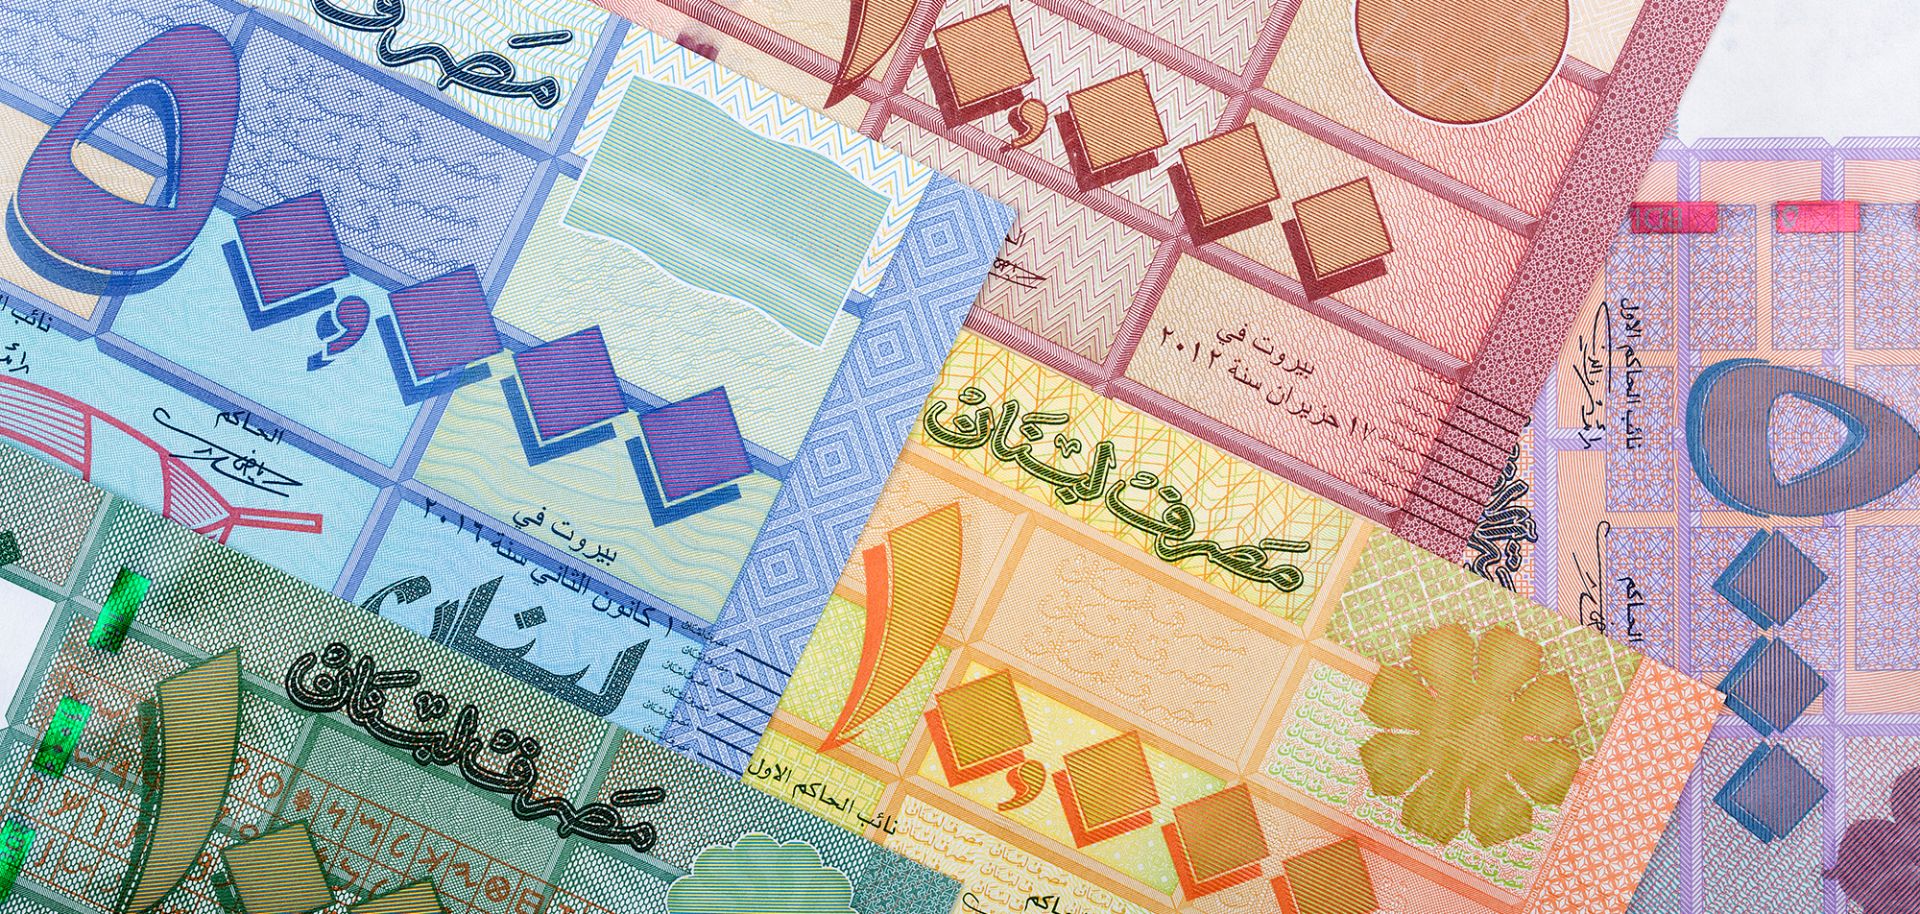
Lebanese pounds.
Lebanon is highly likely to default on a $1.2 billion, 10-year eurobond that matures March 9. Even if it makes that payment, the country's finances are near collapse. When that happens it will accelerate a crisis in the country's insolvent banking sector, probably deepening its ongoing currency crisis and setting off a downward economic spiral threatening social and political stability. Perverse as it sounds, the government might decide it is better to default now rather than using up scarce foreign exchange and putting off what financial markets already consider inevitable. The only real question is whether the government can muster the political will to act now — and penalize the political and financial elite which benefits from Lebanon's rentier-type economy, in which citizens are dependent on government largesse often according to sect and political affiliation — or whether it will give priority to external creditors at the expense of the...